EU diesel hit €2.159, its highest since 2005, and October looks worse
Europe's dearest ever litre arrived three weeks before the peak the ECB expects
European drivers paid more for fuel in the week of 14 September than in any week the European Commission has measured since 2005. The bulletin is the pan-European number, and it lands with a forecast attached: ECB experts expect diesel refining margins to peak in October. Two things follow from that date, and neither is the one filling French television bulletins.
EU petrol hit €2.063 and diesel €2.159 in the week of 14 September
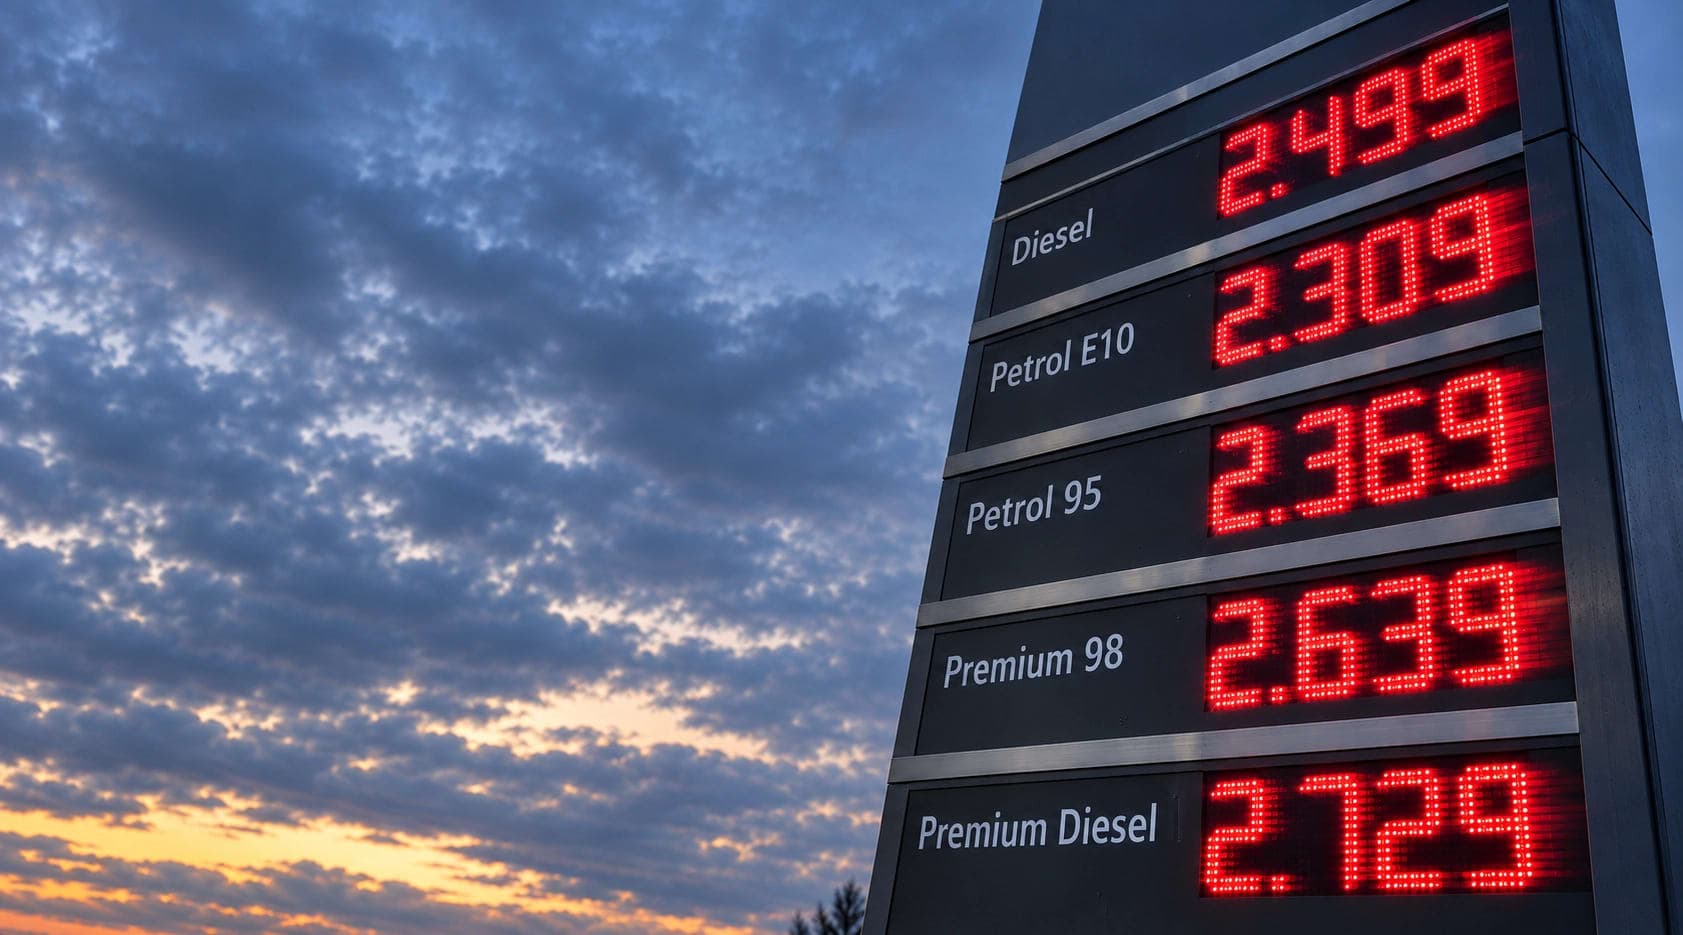
The Commission's Weekly Oil Bulletin, published on 17 September using prices reported for 14 September, put the weighted EU average at €2.063 a litre for petrol and €2.159 for diesel. Both are the highest readings in a series that starts in 2005. Petrol's previous peak was set in 2022; diesel last came close in April this year. France averaged €2.29 on that date and was not even the most expensive market: Germany, the Netherlands, Denmark and Finland were all higher. That week also produced the moment when records were set on both sides of the Atlantic in a single week.
The ECB expects diesel margins to peak in October, petrol's peaked in August
Refining margins, not crude, are doing most of the damage. ECB experts told Euronews that on refined diesel futures dated 16 September, the diesel margin is expected to peak in October, while petrol margins already peaked in August. Brent was still above $100 a barrel on Monday after climbing roughly a fifth in September, so crude will not rescue the pump. The ARA diesel crack stood at $85.16 a barrel on 16 September, level with jet fuel, leaving refiners no reason to favour diesel. That margin split is the same one that pushed diesel above petrol across Europe earlier this summer.
Saudi Arabia shut a 4 million barrel bypass and Russia extended its export ban
Two supply events in the same week explain the October shape. Saudi Arabia temporarily shut its East-West Pipeline after attacks on the crude system in the Riyadh and Madinah regions, announced by the Saudi Press Agency on 11 September. Saxo's head of commodity strategy Ole Hansen put the line's recent throughput at an estimated 4 to 5 million barrels a day, because it had become the main bypass around the Strait of Hormuz after Gulf shipping was disrupted earlier this year. Aramco then cancelled or delayed September deliveries to European buyers, and Poland's Orlen contracted 16 extra cargoes to replace the missing Saudi supply. Russia extended its full diesel export ban through the end of October, as reported by Vedomosti on 15 September. Physical prices followed: Platts assessed north-west European diesel cargoes at a record $1,642.25 a tonne on 15 September.
France has 16 percent of stations short, and 91 percent sit with one company
The queues in France are not a supply failure. The economy ministry counted 16 percent of stations short of at least one fuel on Monday 21 September, up from 13 percent two days earlier, and economy minister Roland Lescure told France Inter that 91 percent of those outages are at TotalEnergies sites. Francis Pousse, who heads the Mobilians retailers' union, said the same thing: the independents are not running dry. The cause is the price cap TotalEnergies has run since March 2026, which pulls drivers across to its 3,600 stations faster than the group can refill them. French refineries are running at full capacity, strategic stocks are full, and Lescure put the government's supply visibility at six to eight weeks. Diesel is the least affected fuel at 13 percent, against 27 percent for SP95.
Germany cuts 17 cents on 1 October, Sweden adds a krona the same day
National policy is pulling in opposite directions in the same month. Germany and the 16 Lander agreed on 18 September to cut energy tax by 14 cents a litre from 1 October to 31 December, about 17 cents at the pump once VAT follows, at a cost of €2.5 billion, with a legal price cap targeted for January 2027. Sweden moves the other way on the same date: its fuel taxes are already at the EU minimum, so 1 October adds roughly one krona to petrol, and the temporary carbon tax cut of SEK 2.40 a litre lapses on 1 December for about three kronor more. Norway's reduction ended on 1 September and Austria's 1.9-cent cut expires this month.
AutoNext Take
France is not running out of fuel, and the pictures suggesting otherwise are the least useful thing on screen. Its refineries are at full capacity, its strategic stocks are full, and the economy minister has placed 91 percent of the dry pumps inside a single retail network, where a price cap TotalEnergies chose to run since March draws drivers past the independents faster than 3,600 sites can be resupplied. That is a queue, not a shortage, and the fuel in shortest supply is SP95 rather than the diesel everyone is talking about. The honest caveat is that this only holds while the imports hold, and Lescure's own visibility runs out in six to eight weeks.
What actually decides the next two months is a calendar, and it is unusually legible. The ECB expects the diesel margin to peak in October; Germany's 17 cents arrive on 1 October; Sweden's tax rises the same day and again on 1 December; Austria's relief lapses in nine days. If the Commission's bulletin prints below €2.159 in the first week of November, the margin forecast held and Europe paid its worst price in the week of 14 September. If it is still climbing then, the tax cuts were spent into a rising market and the second round will cost governments considerably more than €2.5 billion.